Wildfire Risk & Insurance in the Berkeley and Oakland Hills: What Buyers and Sellers Need to Know
Quick Answer
Homes in the Berkeley and Oakland hills sit in or near designated high fire-severity zones, which increasingly affects insurability, premiums, and required disclosures. If you're buying or selling in the hills, insurance should be sorted out early in the process—not left until a week before closing.
Why This Matters More Than It Used To
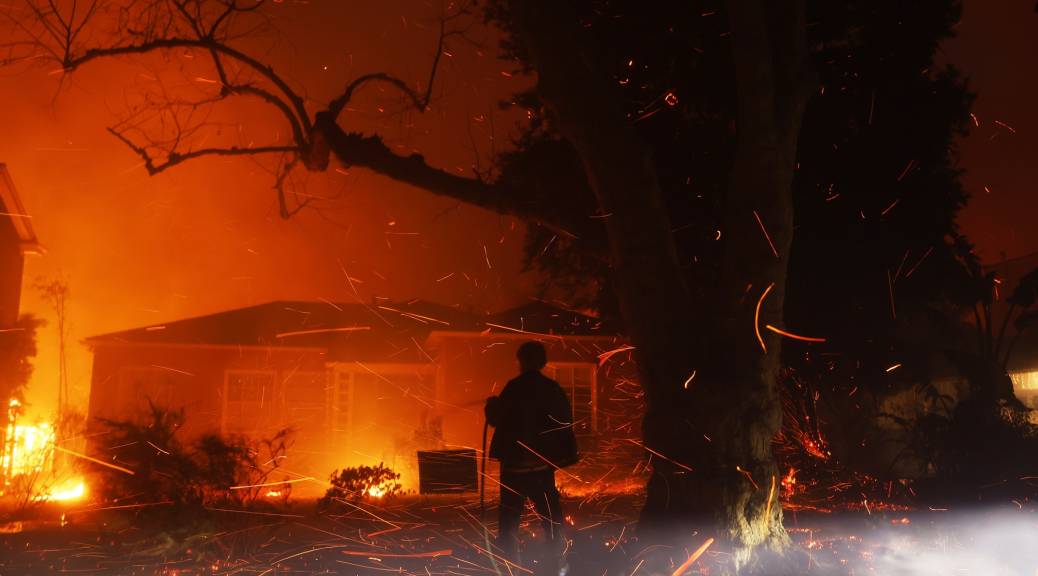
Following the 1991 Oakland Hills fire, this region has always taken wildfire risk seriously, but the insurance market has tightened significantly in recent years as major carriers have pulled back from writing new policies in high-risk zones statewide. Getting a quote is no longer a formality—it can materially affect a deal's timeline and even its viability.
What Sellers in the Hills Should Do Early
- Get an insurance quote before listing, not after accepting an offer. If your own carrier has non-renewed or a buyer's preferred carrier won't write a new policy, you want to know that before you're in escrow.
- Document defensible space and hardening work. Fire-resistant roofing, cleared brush, and ember-resistant vents—this documentation can be the difference between an easy quote and a declined application.
- Disclose accurately. California requires disclosure of a property's location within a state-designated fire hazard severity zone—this isn't optional, and buyers will independently verify it.
What Buyers Should Do Before Writing an Offer
- Get a real insurance quote during your inspection contingency period, not after. A property that seems affordable can become materially more expensive once a realistic premium—or a FAIR Plan policy—enters the picture.
- Understand the California FAIR Plan as a fallback option (California's insurer of last resort for high-risk properties) — it typically costs more and covers less than standard policies, so budget accordingly if it's your only option.
- Ask sellers directly about hardening upgrades—defensible space, roofing material, vent screens—since these affect both risk and insurability.
The Bottom Line
Wildfire risk doesn't have to be a dealbreaker in the hills — plenty of transactions close successfully every year — but it needs to be addressed at the start of the process, not the end. Loop in an insurance broker who specializes in high fire-severity zone properties before you list or before you get too deep into an offer.
This is general information, not insurance or legal advice. Fire hazard zone maps and insurance availability change—confirm current status with CalFire's zone maps and a licensed insurance broker.
Buying or selling in the Berkeley or Oakland hills? Let's talk through the insurance picture early so it doesn't become a late surprise.
About The Parker George Team
Robert Parker and Josie George lead The Parker George Team , a Berkeley-based real estate team serving Berkeley, Oakland, Kensington, El Cerrito, Piedmont, Alameda, Albany, Emeryville, and Richmond. Robert holds the Certified Luxury Home Marketing Specialist (CLHMS) designation, and the team has been recognized by America's Best and featured in the San Francisco Business Times. Licensed with the California DRE (Robert #01923837, Josie #01990905), the team is based at 801 Delaware St, Berkeley, CA 94710.
Check out this article next